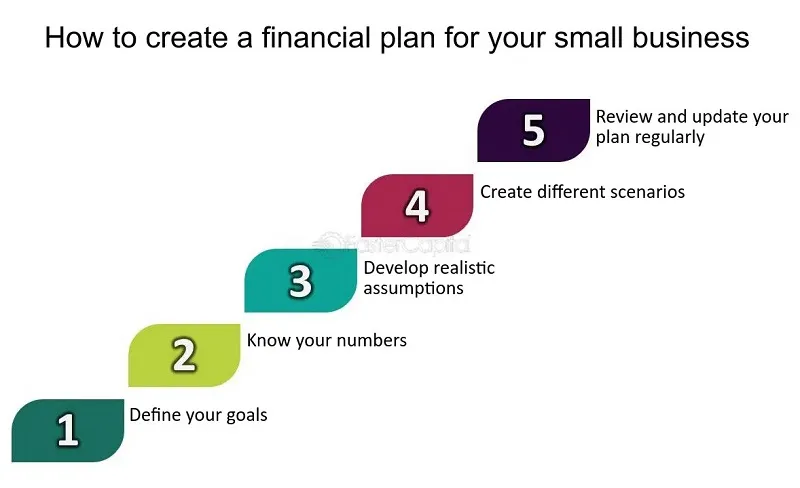
Running a small business involves more than offering great products or services—it requires sound financial planning to ensure sustainability and growth. Without a clear financial roadmap, small businesses risk mismanaging cash flow, overspending, or missing opportunities for expansion. In this article, we’ll explore five essential financial planning tips to help your small business thrive.
Create a Comprehensive Budget
Budgeting is the cornerstone of financial planning for any small business. A well-structured budget serves as a roadmap, guiding you in allocating resources efficiently while keeping spending in check.
Why Budgeting Matters
- Tracks income and expenses, highlighting areas for cost-cutting.
- Ensures funds are available for critical business operations.
- Helps in planning for growth and unforeseen expenses.
Steps to Create an Effective Budget
- Assess Your Finances: Analyze historical financial data, including revenue, costs, and profit margins.
- Categorize Expenses: Divide expenses into fixed and variable categories.
- Set Revenue Goals: Establish realistic income targets based on market trends and past performance.
- Review and Adjust Regularly: Update your budget to reflect changing circumstances or unexpected expenses.
Tools for Budgeting
Consider using financial software like QuickBooks, FreshBooks, or Wave, which can simplify budgeting, generate reports, and track expenses automatically.
Manage Cash Flow Effectively
Positive cash flow is critical for the day-to-day functioning of a business. Many small businesses fail due to cash flow mismanagement rather than a lack of profitability.
Understand Cash Flow
Cash flow is the net amount of money moving in and out of your business. Positive cash flow means you have more money coming in than going out.
Tips for Cash Flow Management
- Invoice Promptly: Send invoices immediately after services or products are delivered.
- Encourage Early Payments: Offer discounts for customers who pay ahead of schedule.
- Delay Payables Strategically: Negotiate longer payment terms with suppliers.
- Build a Cash Reserve: Maintain a reserve fund to handle seasonal fluctuations or emergencies.
Separate Business and Personal Finances
Blurring the lines between business and personal finances is a common mistake among small business owners. This can lead to tax complications, inaccurate accounting, and even legal risks.
- Simplifies bookkeeping and tax reporting.
- Protects personal assets from business liabilities.
- Improves your credibility with banks and investors.
Invest in Growth Strategically
Investing in growth is essential for long-term success, but it should be done strategically to avoid overextending your resources.
Identify High-Impact Investments
- Marketing: Focus on high-ROI strategies.
- Technology: Upgrade software, hardware, or automation tools.
- Employee Training: Develop your team’s skills.
Assess Your ROI
Before committing to any investment, analyze its potential return. Estimate the revenue it will generate and compare it to the costs.
Prepare for Taxes and Legal Obligations
Taxes and legal compliance can be overwhelming, but proactive planning can save time, money, and stress. Understand income, sales, and payroll tax obligations, renew licenses on time, and regularly review contracts.
Bonus Tips for Thriving Financially
- Create an emergency fund with 3–6 months’ worth of operating expenses.
- Conduct regular financial reviews using profit margins, customer acquisition costs, and gross revenue.
- Seek expert advice so your plans align with your business goals.
Frequently Asked Questions (FAQs)
How can I improve cash flow? Improve it by invoicing promptly, offering early payment discounts, negotiating better payment terms, and building a cash reserve.
Why separate personal and business finances? Separation simplifies bookkeeping, protects personal assets, and keeps tax reporting accurate.
Keep learning